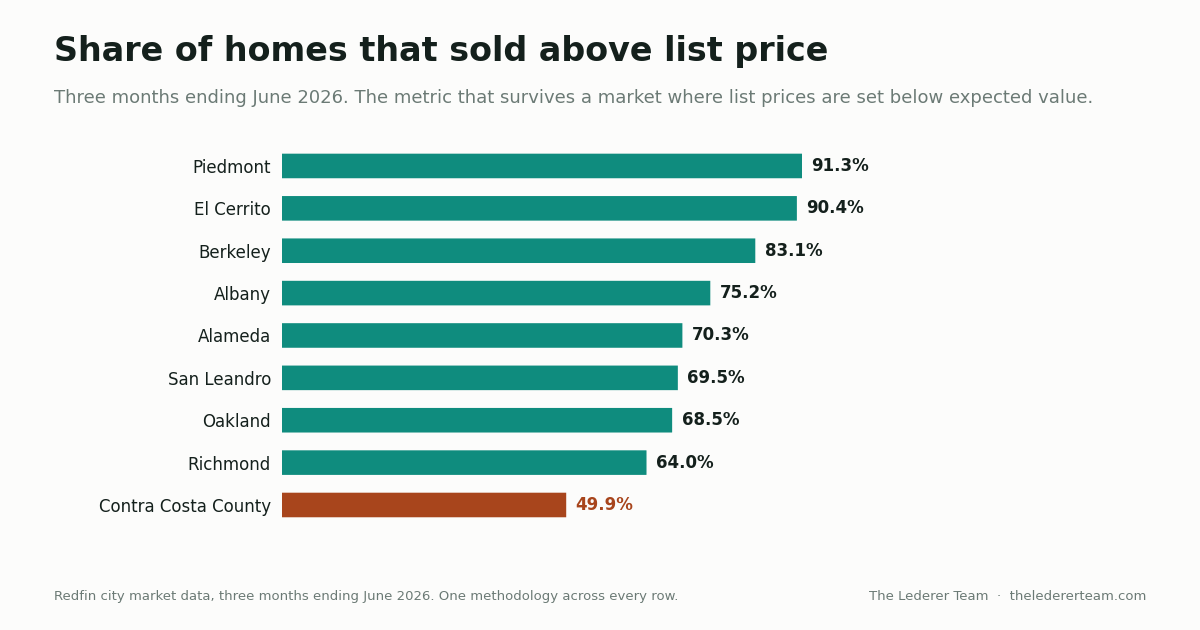
Short answer: Over the three months ending June 2026, 83.1% of Berkeley homes and 68.5% of Oakland homes sold above list, per Redfin, on 15 and 20 median days on market. Nothing done after a listing appears changes that math. Fewer offers come from three things done in advance: underwritten financing, a decision about the $1,249,125 jumbo line, and disclosures read before you care about the house.
Why preparation has to happen before the house exists
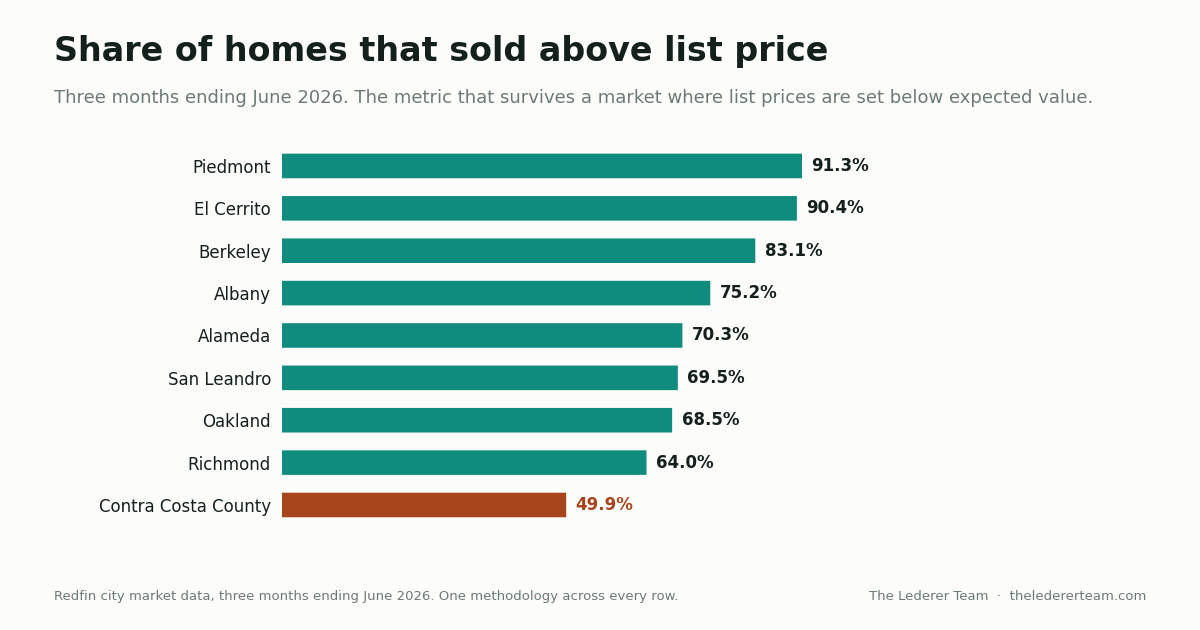
The market you are preparing for, per Redfin, three months ending June 2026:
Market | Median sale | Days on market | Sold above list | Homes sold |
|---|---|---|---|---|
Piedmont | $3,198,260 | 13 | 91.3% | 46 |
El Cerrito | $1,179,358 | 14 | 90.4% | 52 |
Berkeley | $1,509,179 | 15 | 83.1% | 228 |
Albany | $1,484,192 | 16 | 75.2% | 33 |
Alameda | $1,184,855 | 17 | 70.3% | 158 |
San Leandro | $888,017 | 15 | 69.5% | 127 |
Oakland | $898,511 | 20 | 68.5% | 805 |
Richmond | $649,646 | 17 | 64.0% | 207 |
Contra Costa County | $842,623 | 18 | 49.9% | 992 |
Two things follow. A 13-to-20 day median means the window between a listing appearing and offers being due is about two weekends, so anything unfinished when the house appears stays that way. And a market where 64% to 91% of homes sell above list in the inner East Bay cities — and 49.9% even in Contra Costa County — is not full of surprised sellers — it is a deliberate pricing convention, covered in why East Bay homes sell over asking. The list price is a starting gun, not an estimate.
Behind it: East Bay inventory ran 20% to 25% below last year as of June 2026, per RE/MAX Accord, which put the East Bay single-family median at $1,235,000 in May 2026, up 7.4% on 1,465 closed sales.
Financing certainty, and the $1,249,125 line
FHFA announced the 2026 conforming loan limits on November 25, 2025. The baseline one-unit limit is $832,750, and the high-cost ceiling is $1,249,125. Alameda County and Contra Costa County are both at the ceiling. A one-unit loan above $1,249,125 in either county is a jumbo.
Do the arithmetic before you shop, because it changes what a down payment is for. At Berkeley's $1,509,179 median, staying under the conforming ceiling takes about $260,054 down — roughly 17.2%. Below that you are in jumbo underwriting, a different approval process, not just a different rate. More in jumbo versus conforming in the East Bay.
Freddie Mac's Primary Mortgage Market Survey put the 30-year fixed at 6.65% and the 15-year at 5.95% for the week ending August 20, 2026, against 6.58% a year earlier. Useful context, and nearly irrelevant to whether your offer is accepted.
What a seller is pricing is the risk your loan does not close, which is why your lender's structure matters. A mortgage bank processes, underwrites, documents and funds its own loans, and can underwrite to the guidelines of most institutions — so if a program stops fitting, it can switch lender and program while keeping control of the transaction. Confirm specifics with your own lender.
Read the disclosure package before you care about the house
In California, sellers of 1–4 unit residential property deliver a package before you write. Read it cold, while you can still walk away. These obligations are statutory and cannot be waived by an "as-is" sale, so as-is is not an excuse for a thin package. What is in there:
- Transfer Disclosure Statement, Civil Code § 1102 et seq. It asks two separate questions: about alterations or repairs made without necessary permits, and about work not in compliance with building codes. A "no" on one is not a "no" on the other.
- Natural Hazard Disclosure, Civil Code § 1103 et seq., and Mello-Roos / 1915 Act, Civil Code § 1102.6b.
- Lead-based paint, 42 U.S.C. § 4852d, for pre-1978 housing: known hazards, records, the EPA pamphlet and a 10-day inspection period.
- Water heater bracing and smoke alarms, Health & Safety Code §§ 19211 and 13113.8(b) — a written statement of compliance.
- The Seller Property Questionnaire is a C.A.R. form, not a statute, and says on its face it is not a substitute for the TDS.
- Deaths on the property, Civil Code § 1710.2: no duty to disclose a death occurring more than three years before the date you make your offer — your offer date, not close of escrow — and no duty to disclose that an occupant had HIV or died of AIDS-related complications. But no immunity for an intentional misrepresentation answering a direct question.
Then the East Bay items that carry money and lead time. A sewer lateral certificate is required at sale under EBMUD's regional program in Alameda, Albany, Emeryville, Oakland, Piedmont, El Cerrito, Kensington and the Richmond Annex, while Berkeley runs its own separate program under BMC 17.24.130. Oakland also requires sidewalk certification at transfer, OMC 12.04.380. And since January 1, 2026, selling a single-family home or duplex in Berkeley triggers BESO: a Home Energy Score before listing, posted in the MLS Property Notes, then one of three compliance paths before the sale closes. One path hands the work to you — an Upgrade Deposit Form with a $5,000 total deposit, $2,500 from each side, giving the buyer two years to finish the upgrades. Find out which path the seller chose before removing contingencies. This is general information, not legal advice — have your attorney review anything unclear.
Terms, not just price
When most of a market clears above list, price is the entry fee and terms are the differentiator. Preparation lets you offer better terms honestly rather than gamble: underwritten financing shortens a loan contingency because the work is done, not because you waived protection blind, and disclosures read early let you shorten an inspection period because you know what the reports say. For the seller's side of that arithmetic, see how the highest offer is compared.
One East Bay item belongs in preparation rather than escrow: insurability. In the hills, confirm with a licensed insurance broker what a property can be insured for before you are contingency-free. The seller's premium does not transfer to you.
The preparation checklist
Task | When |
|---|---|
Full underwriting, not a rate quote | Before touring |
Your position on the $1,249,125 line | Before touring |
Buyer representation agreement, understood | Before touring |
The disclosure package, both permit questions | Before writing |
Point-of-sale items: sewer lateral, sidewalk, BESO | Before writing |
An insurance quote on the specific address | Before removing contingencies |
How we handle it
Our buyer representation process was developed over 20 years and is mostly front-loaded: financing underwritten first, disclosures read on arrival, point-of-sale obligations identified by city before an offer is drafted. Taken from all offers made by team members in 2021, our buyers wrote an average of 1.5 offers — one team's own count from one year, not a promise about your search.
That works because the people you would otherwise chase are already here: three real estate advisors and six dedicated specialists in finance, mortgage, insurance, estate planning and renovation. Most buyers assemble that cast one referral at a time, and the pieces never talk to each other. Our mortgage advisors act as a fiduciary, and a cohort of private investors can back buyers so they can present all-cash offers. The consultations are complimentary. In 2025 the team ranked in the top 1.5% of agents nationwide.
If you would rather prepare before the listing appears than after you lose it, get in touch.
Frequently asked questions
What is the conforming loan limit in Alameda County in 2026?
$1,249,125 for a one-unit property. Alameda and Contra Costa are both at the FHFA high-cost ceiling for 2026, announced November 25, 2025, against a national baseline of $832,750. Two-unit is $1,599,375, three-unit $1,933,200, four-unit $2,402,625. Above the one-unit ceiling, you are in jumbo underwriting.
Should I review disclosures before making an offer?
Yes, and in the East Bay the package is usually available before offers are due. Reading it early is what lets you price and structure an offer accurately instead of discovering problems mid-escrow. Read both Transfer Disclosure Statement questions: work done without necessary permits, and work not in compliance with building codes.
Does an as-is sale mean the seller does not have to disclose?
No. Disclosure obligations for 1–4 unit residential property in California are statutory and cannot be waived by an as-is sale. As-is describes the seller's willingness to make repairs, not the duty to tell you what they know. The Transfer Disclosure Statement and natural hazard disclosure still apply.
Who pays for Berkeley's BESO energy requirement?
The seller obtains the Home Energy Score before listing and posts it in the MLS listing, then picks one of three compliance paths before the sale is finalized. One path defers the work to the buyer through an Upgrade Deposit Form: a $5,000 total deposit, $2,500 from each side, and two years to finish. Ask which path was chosen.
How much above asking do East Bay homes sell for?
The honest measure is the share sold above list, not a ratio, because East Bay sellers deliberately list below expected value. Over the three months ending June 2026, Redfin recorded 91.3% of Piedmont sales, 90.4% in El Cerrito and 83.1% in Berkeley closing above list, against 49.9% in Contra Costa County.
Sources
- Freddie Mac Primary Mortgage Market Survey, week ending August 20, 2026 — link
- FHFA 2026 conforming loan limits, announced November 25, 2025 — link
- City of Berkeley, BESO time-of-sale energy requirement, January 1, 2026 — link
- EBMUD Regional Private Sewer Lateral program — link
- City of Oakland, sidewalk certification, OMC 12.04.380 — link
Mark Lederer leads The Lederer Team at Red Oak Realty, with 25+ years and 1,000+ closed transactions across Berkeley, El Cerrito, Oakland, Piedmont and Alameda. To do the preparation before the next listing appears rather than after you lose it, call 510-774-4231 or email [email protected].